Skip to content

FINANCING FOR AGRICULTURE

Business Financing Through Seasonal Production and Sales Cycles

Agricultural businesses and their suppliers often have highly seasonal purchasing, production, storage and sales cycles. Cash is needed well before commodities or products are sold and customers pay, and the gap can strain even a well-run operation.

Business models across the sector differ, and so do their collateral characteristics. Great Elm Commercial Finance provides asset-based lending to middle-market businesses, looking at the strength of your management team and the assets that can support a facility, such as receivables, inventory and machinery and equipment.
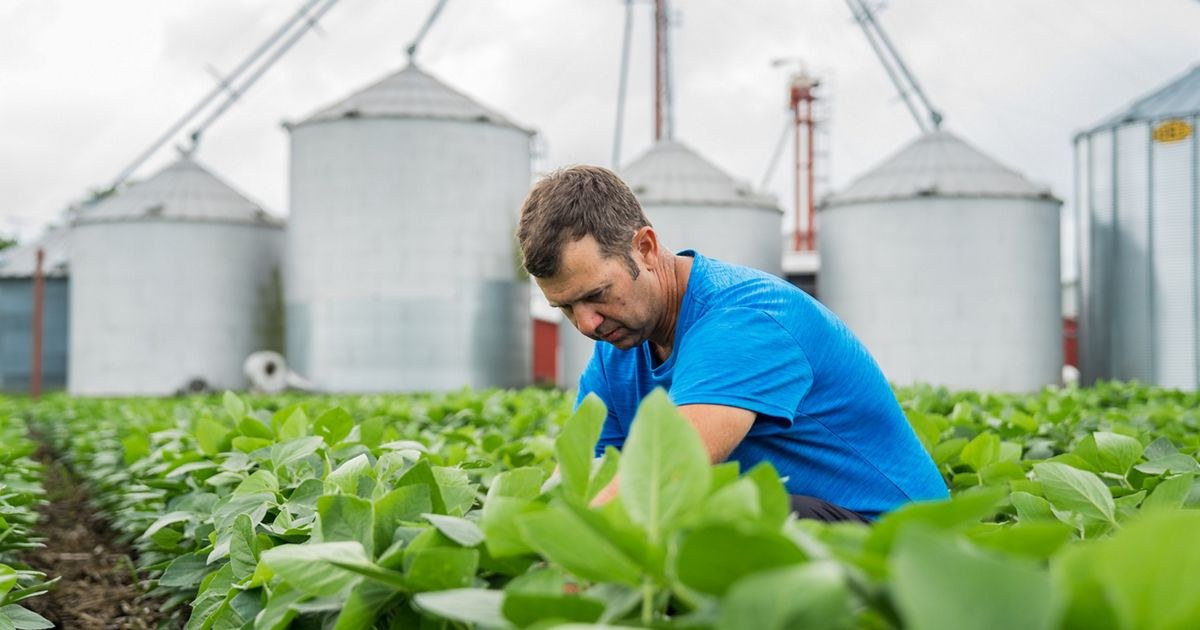
Farmer kneeling in a soybean field inspecting the crop, with grain silos behind

INDUSTRY CHALLENGES

Financial Demands of Agricultural Business Cycles

Agricultural businesses carry costs through long cycles before revenue is realized, and conditions outside their control can shift quickly. These are the pressures we see most.

Understanding them is essential to structuring financing that fits how these businesses operate.

Seed, fertilizer, feed, fuel, labor and other costs often come due in concentrated periods, well ahead of sales proceeds. Working capital is committed before there is revenue to replace it.

Machinery, processing and storage assets require significant upfront investment, and the return builds over many seasons. Those commitments compete with day-to-day operating needs.

Changes in commodity prices and market demand can alter expected revenue between the time costs are incurred and the time product is sold.

Agricultural suppliers, processors and service businesses may invoice commercial purchasers on extended terms, so cash can arrive well after the product has shipped or the work is done.

Stored or in-process inventory ties up capital until it is sold, and its quality, condition and marketability affect how it can be viewed as collateral.

WHO WE FINANCE

Agribusiness Operators We May Finance

We work with established agricultural businesses that have strong management and qualifying assets we can lend against. Eligibility is reviewed individually, based on the business and its collateral. Typical borrowers include the profiles at right.

  • Agricultural suppliers. Input and supply businesses with trade receivables and inventory that can be reviewed as collateral.
  • Processors and packagers. Operations with receivables, processing machinery and qualifying inventory.
  • Commodity-related distributors. Businesses that move and resell agricultural products to commercial customers.
  • Equipment-intensive agribusinesses. Established operations with documented machinery and productive assets.

$5MM–$500MM

Typical Annual Borrower Revenue

Financing availability and eligibility depend on the individual transaction, eligible collateral, and underwriting requirements.

$5MM–$30MM

Typical Target Loan Size

A typical target, not a limit. Loan size depends on the individual transaction, eligible collateral, and underwriting requirements.

FINANCING APPLICATIONS

Capital for Seasonal Operations, Equipment and Collections

Agricultural businesses typically seek capital for three distinct purposes.

Seasonal

Manage Seasonal Operating Requirements

Evaluate funding needs when expenses come ahead of sales, secured by eligible business assets.

Equipment

Finance Equipment and Productive Assets

Support eligible machinery or other operational investments with term financing.

Collections

Bridge Commercial Sales and Collections

Consider borrowing supported by eligible receivables while commercial buyers pay.

RELEVANT FINANCING SOLUTIONS

Asset-Based Financing for Agribusiness

Secured Term Loans may support qualifying equipment or other accepted collateral. A Ledgered Line of Credit may provide revolving borrowing against eligible commercial receivables.

Collateral eligibility depends on ownership, existing liens and applicable statutory rights, and each product is potentially suitable depending on your assets, borrowing needs and underwriting.

Recent Deals

Financing deals that move businesses forward.

Explore our recent financing transactions and discover how we’re helping businesses access the capital they need to grow and succeed.

FREQUENTLY ASKED QUESTIONS

Agriculture Financing FAQs

Answers to common questions about how asset-based financing can support agricultural businesses.

No. Eligibility depends on the type, quality, marketability and condition of the inventory, and on whether any legal rights or restrictions apply. Each situation is reviewed individually.

Discuss Financing for Your Agricultural Business

Great Elm can evaluate your seasonal capital requirements, business assets, receivables and financing objectives.

Contact Our Financing Team

Tell us about your business and what you’re looking to finance. A member of our team will follow up to discuss your needs and potential next steps.