Skip to content

FINANCING FOR FOOD & BEVERAGE

Capital Committed Before Buyers Pay

Food and beverage companies commit capital to ingredients, packaging, equipment, processing and distribution before they collect payment from buyers. Inventory characteristics, customer relationships and changing consumer demand can significantly influence how much working capital a business needs and when.

Great Elm Commercial Finance provides asset-based financing to eligible food and beverage businesses. We evaluate the management team, the operating cycle and the assets available to support the facility, and we structure financing around how the business actually runs.
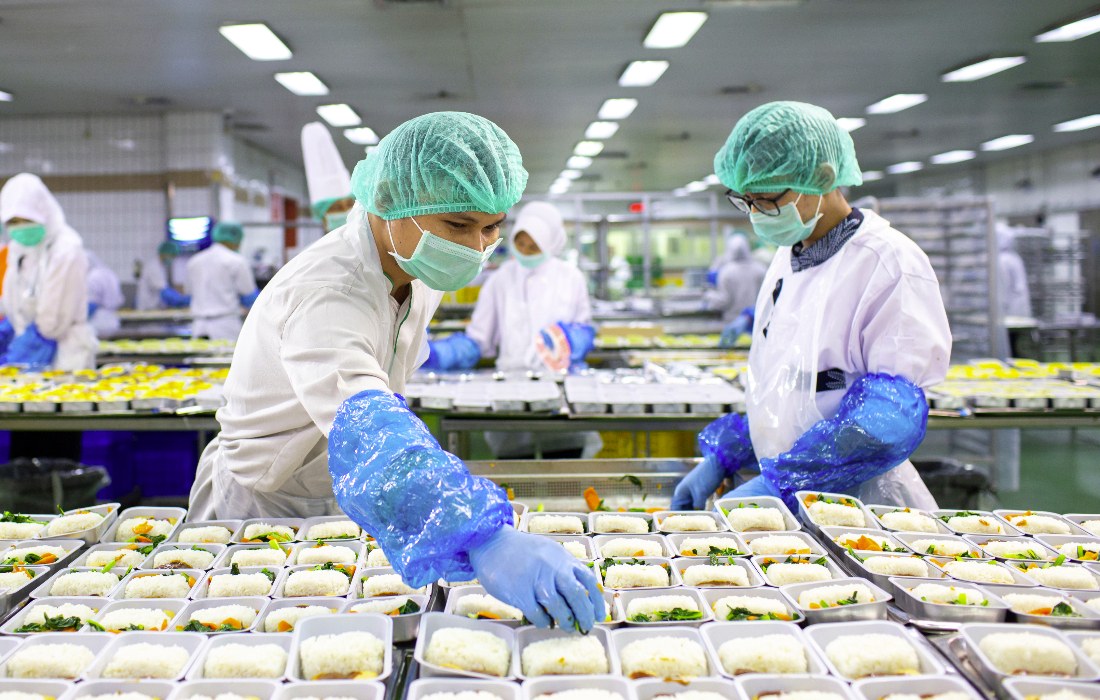
Food production workers in hairnets and gloves plating prepared meals on a packaging line

INDUSTRY CHALLENGES

Cash-Flow Pressures from Production to Retail

Food and beverage businesses spend on production long before finished goods turn into cash. Shelf life, retailer terms, seasonal demand and customer concentration all shape how much liquidity the business needs and when.

Understanding these pressures is the starting point for a financing structure that fits the operating cycle.

Ingredients and packaging are bought and paid for before a single finished unit is sold, often on short supplier terms. Price swings in key inputs can raise the capital each production run requires.

Shelf life and expiration dates limit how long product can be held and affect how it is valued. Inventory that moves slowly can lose value, which changes how collateral is assessed.

Grocers, distributors and foodservice buyers commonly pay after goods have shipped, and sometimes after deductions are resolved. Growing sales to these customers raises the cash waiting on open invoices.

Holidays, harvest cycles and retail promotions require larger production runs well before sales are realized, then leave cash flow uneven in the quieter periods that follow.

WHO WE FINANCE

Food & Beverage Businesses We May Finance

We work with established food and beverage businesses that have eligible receivables, equipment or other qualifying assets we can lend against. Financing depends on the collateral, the business and our underwriting review.

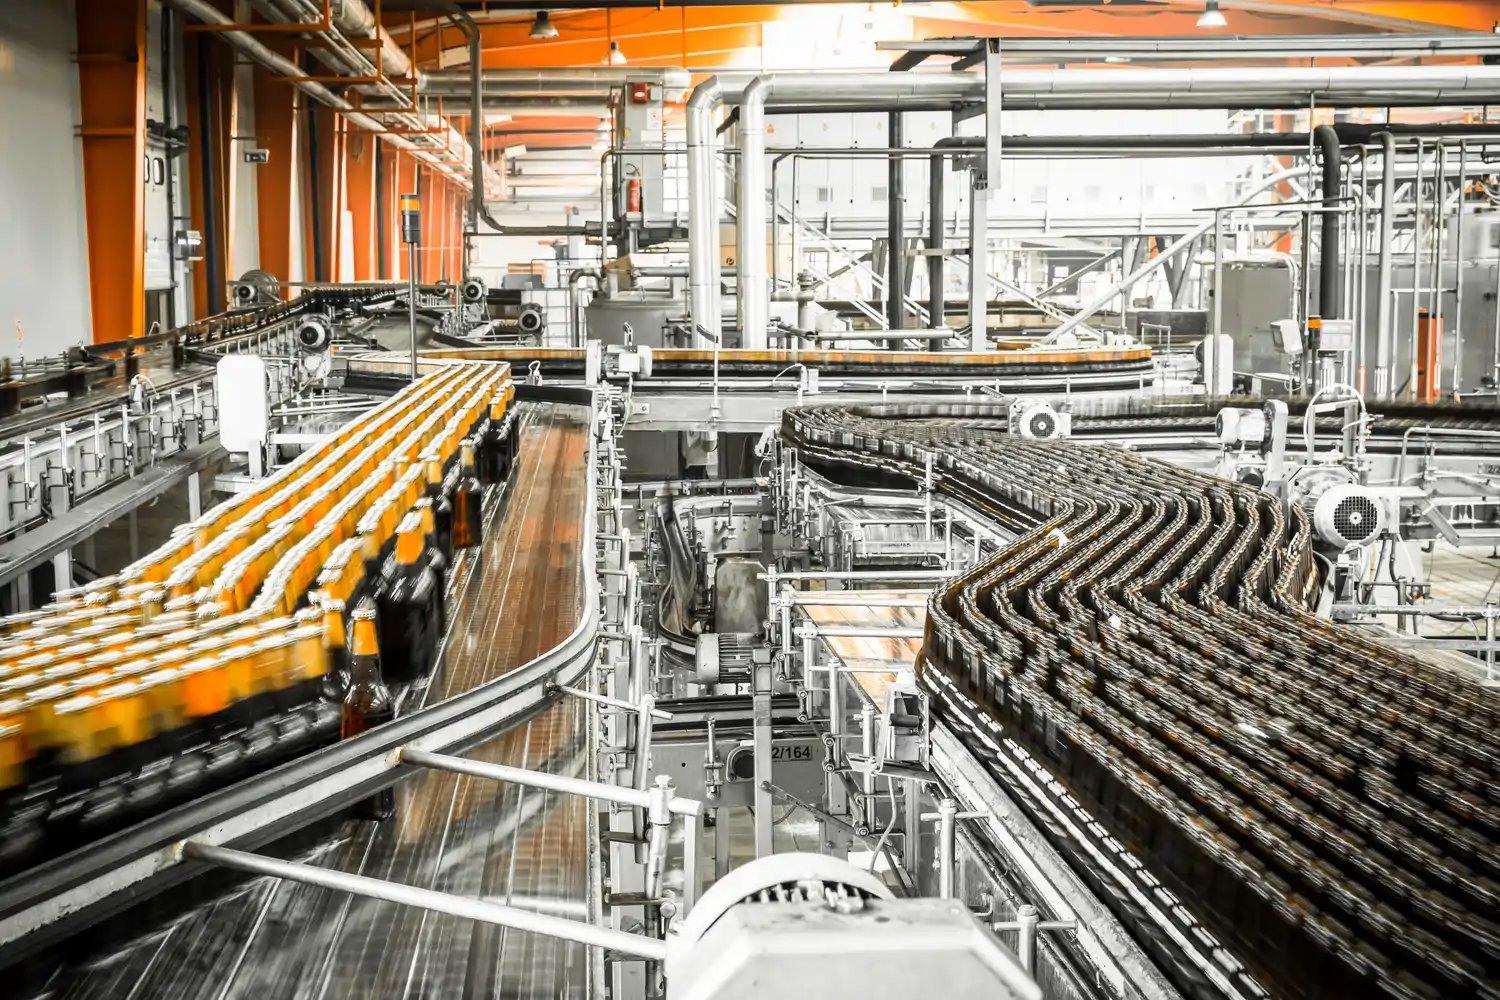
Beverage bottling facility with automated conveyors and processing equipment
  1. 01

    Food Processors and Manufacturers

    Established processors and manufacturers with eligible receivables, inventory and equipment. Financing can strengthen liquidity, support production or replace a credit arrangement that no longer fits the business.

  2. 02

    Beverage Producers and Bottlers

    Beverage producers and bottlers that carry significant equipment and packaging investment and sell through distributors and retailers, where receivables and equipment can support a financing facility.

  3. 03

    Food-Related Distribution Businesses

    Distribution businesses that move food and beverage products to retailers, restaurants and other commercial buyers, with capital tied up in inventory and in invoices owed by those customers.

$5MM–$500MM

Typical Annual Borrower Revenue

Financing availability and eligibility depend on the individual transaction, eligible collateral, and underwriting requirements.

$5MM–$30MM

Typical Target Loan Size

A typical target, not a limit. Loan size depends on the individual transaction, eligible collateral, and underwriting requirements.

FINANCING APPLICATIONS

Capital for Ingredients, Equipment and Distribution

Capital needs in food and beverage run from the receiving dock to the retailer. Depending on the collateral and the transaction, financing can support these priorities.

Production

Fund Production and Purchasing Cycles

Address the capital required for ingredients, packaging and fulfillment while finished product moves toward sale. Availability depends on the type, condition and marketability of eligible assets.

Orders

Support Larger Retail or Distributor Orders

Manage eligible receivables and the added production a larger order demands, so the business can accept growth without waiting on payment from earlier shipments.

Facilities

Invest in Facilities and Equipment

Finance qualifying processing, bottling, storage and other productive assets with term financing supported by eligible collateral.

FINANCING SOLUTIONS

Financing Solutions for Food & Beverage Companies

Great Elm offers financing structures designed for different capital needs. Which one fits depends on your collateral, borrowing needs and existing obligations.

Recent Deals

Financing deals that move businesses forward.

Explore our recent financing transactions and discover how we’re helping businesses access the capital they need to grow and succeed.

FREQUENTLY ASKED QUESTIONS

Food & Beverage Financing FAQs

How asset-based financing can help food and beverage businesses manage production, inventory, customer payment cycles and investment.

A receivables-based facility, such as a Ledgered Line of Credit, can provide borrowing availability against eligible invoices, which can help fund the production a larger order requires.

The creditworthiness and concentration of your customers, invoice age and terms, disputes and deductions, and how receivables are documented all influence which invoices count toward availability.

Term financing supported by eligible machinery and equipment may help fund processing, bottling, packaging or storage assets. Collateral valuation and repayment terms depend on the transaction.

Discuss Financing for Your Food & Beverage Business

From production working capital to equipment investment and growth, Great Elm can review your financing requirements and eligible operating assets.

Contact Our Financing Team

Tell us about your business and what you’re looking to finance. A member of our team will follow up to discuss your needs and potential next steps.