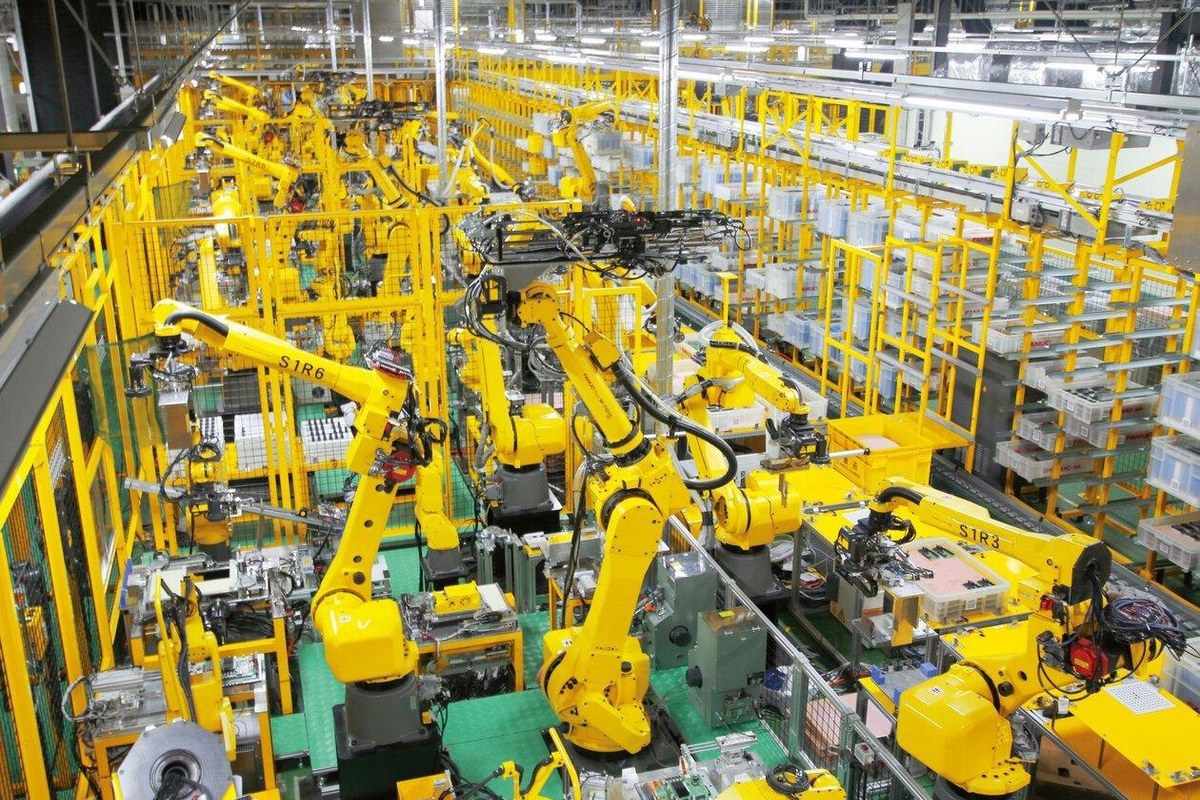
A manufacturer can win a valuable new order and still face a difficult working-capital problem: the business must pay for production well before its customer pays for the finished goods.
Materials may be purchased early. Employees and vendors must be paid during production. Finished products may sit awaiting inspection, shipment or acceptance. Only then might an invoice be issued—and customer payment could come weeks later.
The challenge is not simply the size of the order. It is the mismatch between when cash leaves the business, when an asset exists, when the contract permits invoicing, and when the customer ultimately pays.
Financing a long production cycle starts with a dated cash forecast: compare supplier payments and production costs with available cash, customer deposits, supplier credit and borrowing supported by eligible assets at each stage. The comparison shows when funds are needed—and where even an asset-backed facility may leave a gap.
Follow the order from purchase to collection
Consider a fictional manufacturer producing custom industrial assemblies under a customer order. This is a teaching example, not a real Great Elm customer, typical production lead time or promised financing scenario.
Assume materials must be paid for when received in Week 1, payroll and other production costs are paid as work proceeds, the customer accepts the delivered assemblies and the contract permits invoicing in Week 7, and payment arrives four weeks later. There are no customer deposits or progress billings in this example.
| Illustrative stage | What is happening | Primary cash pressure | Financing or collateral question |
|---|---|---|---|
| Week 0: order accepted | The manufacturer commits capacity and starts planning | Upcoming material and labor payments; no customer deposit | An order is not automatically a financeable receivable; what rights and payment milestones exist? |
| Week 1: materials purchased | Materials arrive and the supplier is paid on receipt | Cash leaves before the finished product can be invoiced | Does the company own the materials? Where are they held, and would a particular facility consider them eligible inventory? |
| Weeks 2–5: production | Labor and overhead turn inputs into unfinished assemblies | Payroll and conversion costs are paid as work proceeds | Work-in-process may have accounting value, but is it owned, marketable and accepted under the actual borrowing-base definitions? |
| Week 6: completion and inspection | Assemblies pass the manufacturer's inspection and await delivery and customer acceptance | Handling, freight and other costs may still be due before collection | How do title, location, saleability, quality and acceptance terms affect inventory eligibility? |
| Week 7: delivery and invoicing | Customer accepts delivery and an invoice is issued under the assumed contract | Customer payment is still outstanding | Is there a valid, undisputed eligible invoice, and are any offsets or other conditions relevant? |
| Week 11: collection | The customer pays four weeks after invoicing | Collected cash may be needed for the next production run | How are receipts applied under any existing credit and account arrangements? |
In Weeks 1–6, the manufacturer pays for materials and production before this order generates an invoice. If its revolving facility is supported only by eligible receivables, this order may add no receivables-based borrowing capacity during those weeks, even if other outstanding invoices support existing availability. Cash reserves, other eligible collateral, different supplier terms or other funding could narrow the shortfall, but none can be assumed.
The potential funding gap is the cash needed before collection that available sources cannot cover—not the order's expected sales value.
Production costs and financeable assets are different questions
A manufacturer may incur production costs or make cash payments without immediately creating collateral that a lender will accept. Even when those costs are reflected in inventory, their accounting value does not necessarily determine how much financing that inventory can support.
Raw materials: who owns them, and where are they?
Raw materials can represent meaningful working capital tied up before production. Their potential financing value depends on issues such as actual ownership, resale characteristics, condition, inventory location and other rights affecting the goods.
Materials that are readily marketable may present a different assessment from specialized items made for a single customer. A supplier's interest or a customer's ownership rights can also change the analysis.
Work-in-process: value in the factory is not always lending value
Work-in-process (WIP) is particularly easy to misunderstand. The business may have spent substantially on labor and materials, but an unfinished product can be difficult to complete or sell to anyone other than the intended customer.
The OCC's asset-based lending handbook discusses why inventory classes can be treated differently for lending purposes and why WIP can have limited liquidation value. Its observations are supervisory guidance for banks—not a universal rule or any specific lender's underwriting terms.
Do not assume that recording WIP on the balance sheet makes it eligible collateral. Equally, do not assume that no specialized financing arrangement could ever address production-stage requirements; the actual answer depends on the transaction and its documentation.
Finished goods: completed does not always mean available
A finished product may be easier to assess than partially completed goods, but location, title, saleability, specialization and condition still matter.
Goods made exclusively for a particular customer, stored at a third-party location or subject to unusual acceptance conditions can raise questions different from those for standardized stock held at a company-controlled warehouse.
Receivables: the invoice comes after the costs
Once the relevant performance and invoicing conditions have been met, the business may have accounts receivable to discuss with a lender. Those invoices are still subject to eligibility and collectability considerations—such as disputes, offsets and age—under the particular arrangement.
A receivables-backed facility may therefore support a different part of the operating cycle from the early stages when materials and labor first need funding. For product context, see Great Elm's Ledgered Line of Credit overview; the timing and eligibility of any actual advance remain agreement-specific.
Locate the period when cash needs are greatest
The practical financial exercise is to build a short production-to-collection cash timeline rather than estimating capital need only from projected sales.
Start with the actual commitments, and map the expected dates of:
- Supplier deposits, payment terms and material payments.
- Labor, outside processing, freight, overhead and other production outflows.
- Any contractually permitted customer deposits or milestone receipts.
- Completion, delivery, acceptance and when invoicing rights actually arise.
- Expected customer collections.
- Existing credit obligations and the availability supported by verified collateral at each period.
For each period, forecast cash after scheduled receipts and payments before any new borrowing. Identify each dated cash shortfall and compare it with additional credit actually drawable on that date, not credit that might become available only after a later invoice or collection. Drawable availability must reflect eligible collateral, outstanding advances, facility limits, lender-imposed reserves and other contractual restrictions. Do not count the same goods as both eligible inventory and the receivable from their sale at a single cutoff.
Test the projection if production runs longer, a supplier requires earlier payment or customer acceptance is delayed. Collections applied to debt should not be counted as both unrestricted cash and unchanged receivables-backed borrowing availability.
The financing question becomes more precise: At the point the business needs funds, what sources of cash or committed borrowing are actually available? Expected customer payments, unbilled order value and eligible receivables are not interchangeable.
Match the financing discussion to the actual need
A manufacturing company may have several capital requirements at the same time. Before selecting a financing structure, assess whether supplier payment terms, customer deposits or progress billing, production scheduling and existing cash reserves could reduce the gap. Those options depend on the business's actual commercial arrangements.
Recurring working capital: The business needs funding for materials, payroll and operations as orders move toward collection. A revolving facility may be relevant to assess, but it must be evaluated against assets, eligibility, reporting and the timing of the actual borrowing need.
Equipment and capacity: A new machine, facility improvement or expansion is a capital-investment decision, not the same as funding a temporary receivables gap. A separate term-financing discussion may be more appropriate, depending on assets, repayment capacity and the structure proposed.
Transactions or refinancing: A manufacturer acquiring another operation, changing lenders or restructuring existing obligations needs a broader view of uses of capital and the credit arrangements already in place.
No single product name proves that every phase of production can be financed. The useful outcome of the analysis is a realistic view of both the supportable borrowing opportunity and any cash requirement that remains uncovered.
Questions to bring to a financing conversation
Before approaching a lender or advisor, consider these questions:
- What is the normal length of an order from purchase to collection, and where does the peak cash need occur?
- Which inventory is raw material, work-in-process or finished goods, and where is it held?
- Who legally owns materials, customer-funded tooling, consigned stock and goods awaiting acceptance?
- Which customer deposits, progress billings or credits change the cash timeline?
- What portion of receivables is current and undisputed, and which records support it?
- How much of the peak cash requirement remains uncovered after supplier credit, customer receipts, unrestricted cash balances and borrowing actually drawable when needed are considered, including the effect of any lender-imposed reserves?
- Is the primary capital need recurring working capital, new equipment, a refinancing or a combination?
A financing structure should be tested against the production and cash-conversion cycle—not just the size of the next order.
For an overview of potential commercial financing options, see Great Elm Commercial Finance's financing solutions. To discuss a manufacturing production-to-collection need, contact Great Elm's team. Any particular facility must be evaluated against the business's actual assets, financing needs and transaction terms.
Keep reading
More from Great Elm
Why Borrowing Availability Can Fall Even When Sales Grow
Higher sales do not always mean more available credit. See how eligible receivables, reserves and outstanding borrowing change actual lending headroom.
Changing Lenders? What to Prepare for an Asset-Based Lending Transition
Considering asset-based lending to replace a conventional bank line? Learn what to prepare, how diligence works, and what to coordinate before the transition.
Sterling Commercial Credit Rebrands as Great Elm Commercial Finance
Sterling Commercial Credit rebrands as Great Elm Commercial Finance, expanding secured lending solutions nationwide.
News
Company news
Sterling Commercial Credit Rebrands as Great Elm Commercial Finance
Sterling Commercial Credit rebrands as Great Elm Commercial Finance, expanding secured lending solutions nationwide.